Why Insurance Matters on a Cross-Country Move
When your belongings travel 4,000 kilometres across the country, they spend a week or more on a truck, get loaded and unloaded multiple times, and sometimes sit in a transfer warehouse between trailers. Every one of those touchpoints is a moment where something can be scratched, dropped, or crushed. On a local move across town, the exposure window is a few hours. On a cross-Canada move, it can be ten days. That is exactly why understanding your insurance options is one of the most important parts of planning a long distance relocation.
Most Canadians assume that hiring a reputable mover means their possessions are fully insured. The reality is more nuanced. The standard liability that comes built into every quote is usually based on weight, not the actual value of your goods — and the gap between those two numbers can be enormous. A reputable long distance moving company will walk you through these options before you sign, but you should arrive at that conversation already knowing the vocabulary.
Key Takeaway: The basic coverage included in your moving quote almost never equals the replacement value of your belongings. Knowing the difference between liability and insurance is what protects you financially if something goes wrong on the highway.
Throughout this guide we will explain the two main coverage models, the third-party policies you can layer on top, how valuation declarations work, and how to file a claim that actually gets paid. We will also cover the often-overlooked coverage gap that opens up during storage-in-transit — a scenario that affects a large share of cross-country moves.
Released Value vs Replacement Value Coverage
There are two coverage frameworks you will encounter on virtually every long distance moving contract in Canada. Understanding them is non-negotiable.
Released Value Protection (Basic Liability)
This is the default, no-extra-cost option. Under released value protection, the mover's liability is capped at a fixed dollar amount per pound (or per kilogram) of the item's weight — commonly around $0.60 per pound, or roughly $1.32 per kilogram. The catch is obvious once you do the math. If a mover damages a 25-pound flat-screen television worth $2,000, released value pays out about $15. The settlement is tied to weight, not value, so dense-but-cheap items are over-protected while light-but-expensive items are dramatically under-protected.
Replacement Value Protection (Full Value Protection)
Under full value protection, the mover is liable for the cost to repair, replace, or pay the current market value of any item that is lost or damaged. This is the coverage most families actually want for a cross-country move. It costs extra — typically a percentage of the total declared value — but it means a damaged $2,000 television gets you a $2,000 resolution, not a $15 cheque.
Always ask your mover to put the coverage tier in writing on the bill of lading. Verbal assurances are worthless during a claim. If you are comparing carriers, build coverage into your decision the same way you would when you evaluate what to look for in long distance movers.
A trustworthy cross-country moving company will never push you toward basic liability to keep the quote artificially low. If a mover downplays coverage or refuses to explain valuation clearly, treat it as a red flag.
What a Mover's Basic Liability Actually Covers
Basic liability is a legal minimum, not a comprehensive safety net. It is important to understand precisely what it does and does not promise so you are not caught off guard.
Under released value protection, the carrier is responsible for goods that are lost or physically damaged while in their care, up to the per-pound cap. That means if a box goes missing entirely, you are reimbursed based on the box's weight, not the value of what was inside it. A 30-pound box of family photo albums and electronics might settle for under $20 — a result that shocks people who assumed their items were genuinely insured.
Basic liability also typically excludes items you packed yourself unless the damage is to the exterior of the box and clearly attributable to mishandling. This is why professional packing matters so much on long hauls. When a trained crew packs your fragile items, the carrier's liability for those items is far easier to establish. The Canadian Association of Movers publishes consumer guidance on these distinctions at cam-acd.ca, and it is worth reading before you sign anything.
⚠️ Watch out: Basic liability is included by default, which means if you do nothing, you are accepting the lowest possible coverage. You must actively elect higher protection — it is never automatic.
The bottom line: basic liability exists to satisfy the legal floor. For a move worth tens of thousands of dollars, relying on it alone is a financial gamble most families should not take.
Third-Party Moving Insurance Options
Beyond the coverage your mover offers directly, you can purchase standalone moving insurance from a third-party insurer. This is increasingly common for high-value cross-country moves, and it can fill gaps that carrier valuation does not.
Standalone Transit Insurance
Specialty insurers sell all-risk transit policies that cover your goods from origin to destination, including periods in storage. These policies often provide broader protection than carrier valuation — covering things like mysterious disappearance, mould, and certain acts of nature that carrier liability excludes. They are particularly valuable when you are shipping antiques, fine art, or collectibles.
Homeowner's or Tenant's Insurance Riders
Some Canadian home and tenant policies extend limited coverage to personal property in transit during a move. Coverage varies dramatically between insurers, and many policies cap or exclude transit claims entirely. Call your provider and ask specifically about "property in transit during a residential move" — and get the answer in writing.
💡 Pro Tip: Stack your coverage strategically. Use full value protection from your mover for the bulk of your goods, and a third-party rider for a handful of irreplaceable high-value items. This is often cheaper than insuring everything at the highest tier.
When you request quotes, a strong professional long distance movers team will tell you exactly where their valuation ends and where third-party insurance should begin. Understanding these layers also helps you spot which carriers are transparent — a key part of how you manage storage-in-transit on a cross-country move without uninsured exposure.
How Valuation Works and How to Declare It
Valuation is the process of assigning a total dollar value to your shipment so the mover knows their maximum liability. It is the single most important number on your contract when it comes to protection.
Most carriers calculate valuation in one of two ways: a lump-sum declared value for the entire shipment, or a per-pound declared value multiplied by the shipment weight. For full value protection, you typically declare a total that reflects the replacement cost of everything on the truck. If your three-bedroom home contains roughly $60,000 of replaceable goods, that is the number you declare — not a lowball figure to save on the premium.
The Deductible Choice
Full value protection usually comes with deductible options. A higher deductible lowers your premium but increases your out-of-pocket cost per claim. For a long haul, a moderate deductible often strikes the best balance.
Create a written home inventory with photos and approximate values before the truck arrives. This single document does more to support an accurate valuation — and a successful claim — than anything else. It also dovetails with the broader hidden costs of long distance moving you should budget for.
Under-declaring to save money is a costly mistake. If you declare $20,000 on a $60,000 shipment, a partial-loss claim is settled proportionally — meaning you recover a fraction of your actual loss. Always declare the honest replacement value.
What Is Covered and What Is Excluded
Even with full value protection, no policy covers everything. Knowing the standard exclusions prevents nasty surprises at claim time.
Commonly Covered
- Items damaged by the crew during loading, transport, or unloading
- Goods lost while in the carrier's possession
- Damage from accidents involving the moving vehicle
- Crushing or impact damage to professionally packed cartons
Commonly Excluded
- Owner-packed boxes (PBO): Damage inside boxes you packed yourself, unless the carton shows clear external mishandling
- Cash, jewellery, documents, and irreplaceables: These should travel with you, not on the truck
- Perishables, plants, and hazardous materials
- Pre-existing damage and normal wear
- Items of "extraordinary value" not declared in advance (often anything over $100 per pound)
⚠️ Declare high-value articles: Most contracts require you to specifically list items worth more than a set threshold per pound. If you do not declare your $8,000 watch or original artwork, it falls outside coverage entirely.
A reputable interprovincial moving company will hand you a written list of exclusions and walk through it line by line. If your fragile or specialty items fall into a grey zone, that is the moment to add a third-party rider or arrange custom crating. Reviewing exclusions carefully is just as important as confirming the carrier's licensing through resources like the Better Business Bureau at bbb.org.
Storage-in-Transit and the Coverage Gap
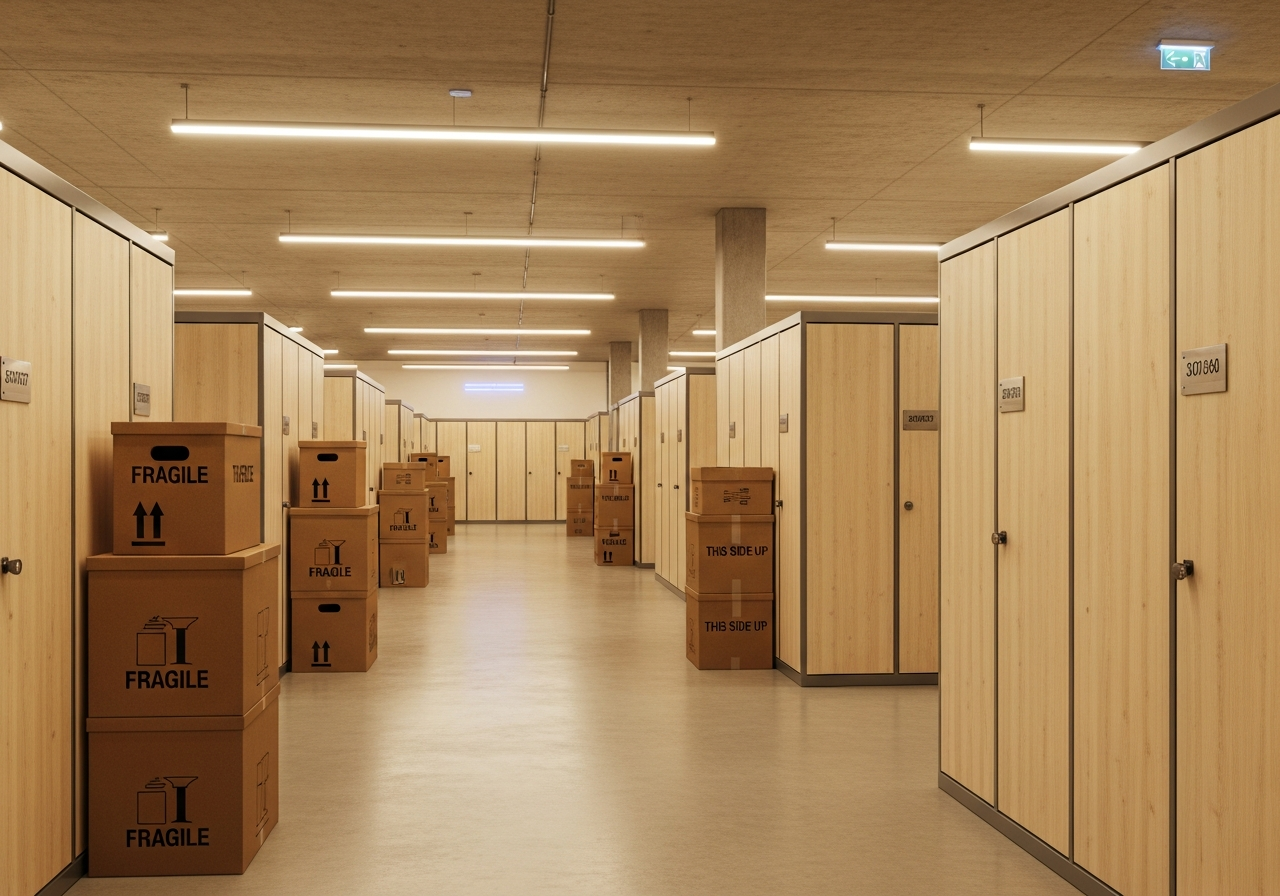
Cross-country moves frequently involve a period of storage-in-transit (SIT) — when your goods sit in a warehouse because your new home is not ready, or because the carrier is consolidating shipments. This is where many homeowners discover a dangerous coverage gap.
Some carrier valuation policies cover goods only while they are physically in motion, with limited or no protection during warehouse storage. Others extend coverage for a fixed number of days (often 30 to 90) before storage transitions to a separate warehouse policy with different terms. If your move involves an extended gap between move-out and move-in, you need to confirm in writing exactly how long your coverage follows your goods into storage.
Key Takeaway: Always ask, "Does my full value protection continue while my goods are in storage-in-transit, and for how many days?" Get the answer on paper. This is the most commonly overlooked gap on long distance moves.
If your goods will be stored for an extended period, consider a dedicated storage insurance policy or a third-party transit policy that explicitly includes warehousing. The risks in storage — water intrusion, pest damage, temperature extremes — differ from transit risks and are not always covered by the same policy. You can learn more about how warehousing fits into a cross-country timeline in our deeper guide to storage-in-transit for cross-country moves.
How to File a Claim That Gets Paid
If something is damaged or missing, the difference between a paid claim and a denied one usually comes down to documentation and timing. Follow this process carefully.
- Inspect at delivery. Before the crew leaves, open accessible boxes and inspect furniture. Note any visible damage directly on the delivery paperwork (the inventory or bill of lading) before signing. A clean signature can undermine a later claim.
- Photograph everything. Take date-stamped photos of damaged items, the packaging, and any obvious cause of damage.
- Report promptly. Most carriers require written notice of a claim within a set window — often 30 to 60 days from delivery, though some allow longer. File as early as possible.
- Submit your inventory and valuations. Your pre-move photo inventory becomes the backbone of your claim.
- Keep damaged items. Do not discard anything until the claim is resolved; insurers often want to inspect.
💡 Pro Tip: Do not sign a delivery receipt that says "received in good condition" until you have actually verified the condition. If the crew is rushing you, write "subject to inspection" next to your signature.
A reputable nationwide moving company maintains a dedicated claims department and a clear written process. When you are choosing a carrier, ask how they handle claims and what their average resolution timeline is — it is a strong signal of how they will treat you if something goes wrong. This ties directly into the diligence covered in our guide on what to look for in long distance movers.
Reducing Risk Before Moving Day
The best insurance claim is the one you never have to file. Reducing risk before the truck arrives lowers both your stress and your odds of loss.
- Use professional packing for fragile and high-value items. Carrier liability is far easier to establish for crew-packed cartons than owner-packed boxes.
- Create a detailed photo inventory. Document the condition of furniture and electronics before they are loaded.
- Carry irreplaceables yourself. Jewellery, documents, medications, and small heirlooms should never go on the truck.
- Crate genuine high-value items. Fine art, mirrors, and electronics benefit from custom crating.
- Update your address paperwork early. Coordinate mail forwarding through Canada Post and your CRA address through the CRA change of address service so insurance and claim correspondence reaches you.
Risk reduction and coverage work together. A well-packed, well-documented shipment with honest valuation is both less likely to suffer damage and far more likely to result in a paid claim if it does. If you want a quote that includes proper protection from the start, request a free moving quote and ask the estimator to break down coverage tiers.
Pairing professional packing with full value protection is the single most effective risk strategy for a cross-country move.
What Moving Insurance Costs in 2026
Cost is the question everyone asks, so let us put real numbers to it. Keep in mind these are 2026 estimates that vary by carrier, route, and declared value.
Full Value Protection
Carrier full value protection typically runs about 1% to 2% of the total declared value, adjusted by your chosen deductible. On a $60,000 declared shipment, expect roughly $600 to $1,200 with a moderate deductible. Choosing a higher deductible can bring this down meaningfully.
Third-Party Transit Insurance
Standalone all-risk policies generally range from 1% to 3% of insured value depending on the items, route, and storage duration. Specialty high-value items like fine art may carry higher rates.
Storage Coverage
If your goods will be warehoused for an extended period, expect to add a modest monthly premium tied to the stored value.
Key Takeaway: For most families, full value protection adds 1% to 2% to the total move cost — a small price relative to the value being transported across the country.
When you compare quotes, make sure each carrier is pricing the same coverage tier, or you are not comparing apples to apples. A transparent long distance moving services provider will itemize coverage separately so you can see exactly what you are paying for. Treat insurance as a core line item, not an afterthought, and factor it into your overall budget alongside the other hidden costs of a long distance move.
Frequently Asked Questions
Is moving insurance mandatory in Canada?
No, but basic liability (released value protection) is automatically included on every contract. It is the legal minimum and pays only a small amount per pound. Upgrading to full value protection or buying third-party insurance is optional but strongly recommended for cross-country moves.
What is the difference between valuation and insurance?
Valuation is the carrier's liability program — it sets how much the mover will pay if they damage your goods. Insurance is a separate product from an insurance company that can cover risks valuation excludes. Many movers offer valuation but are not licensed to sell true insurance, which is why third-party policies exist.
Are items I packed myself covered?
Generally only if the carton shows clear external damage attributable to mishandling. Damage inside an owner-packed box with no external sign of mishandling is usually excluded. For full coverage on fragile items, have the crew pack them.
Does my home insurance cover a long distance move?
Sometimes, but coverage for property in transit varies enormously and is often capped or excluded. Call your provider, ask specifically about residential moves, and get the answer in writing before relying on it.
How long do I have to file a claim?
It depends on the carrier, but written notice is commonly required within 30 to 60 days of delivery. Note any visible damage on the paperwork before signing, and file as soon as possible.
What should I never put on the moving truck?
Cash, jewellery, important documents, medications, and small irreplaceable heirlooms. These are typically excluded from coverage and should travel with you personally.
Does coverage continue while my goods are in storage?
Not always. Some valuation policies cover transit only, while others extend coverage into storage-in-transit for a limited number of days. Confirm in writing how long your protection follows your goods into a warehouse.